Global Diesel Shortage Could Last Into 2027 as Storage Levels Fall
The global diesel market is facing another period of supply pressure, with low inventories, disrupted supply flows and constrained refining capacity raising concerns that tight market conditions could continue into 2027.
A new Reuters analysis reports that the global diesel shortage is unlikely to ease before next year, citing historically low inventories and ongoing disruptions to major supply routes.
The latest outlook is significant because diesel is essential to freight transportation, agriculture, manufacturing, construction and other energy-intensive activities. When inventories fall, buyers can become increasingly sensitive to refinery outages, export changes, shipping disruptions and regional supply imbalances.
Global Diesel Inventories Remain Under Pressure
One of the clearest indicators of the current diesel market is the level of physical inventories.
U.S. Energy Information Administration data shows U.S. distillate fuel oil stocks at approximately 107.9 million barrels on September 11, 2026.
The EIA’s September 2026 Short-Term Energy Outlook expects U.S. distillate inventories to fall below 100 million barrels and remain below the 2021–2025 five-year low through much of 2027. The agency also expects tight global distillate markets to contribute to elevated diesel prices.
These inventory conditions are important because diesel supply depends not only on crude oil availability, but also on refinery capacity, product yields, storage and the ability to move refined products between markets.
Why the Diesel Shortage Could Continue Into 2027
The current diesel shortage is being influenced by several factors at the same time.
Geopolitical disruptions have affected important petroleum supply routes, while refinery outages and reduced availability from major producing and exporting regions have placed additional pressure on refined-product markets. Reuters reports that these disruptions have contributed to historically low diesel inventories and elevated prices.
At the same time, the global refining system has limited flexibility when several regions require additional diesel simultaneously.
A refinery cannot simply increase diesel production indefinitely. Output depends on crude availability, refinery configuration, operating rates, maintenance schedules and the economics of producing middle distillates.
That makes diesel particularly sensitive to unexpected refinery disruptions.
Storage Levels Are Becoming a Critical Market Indicator
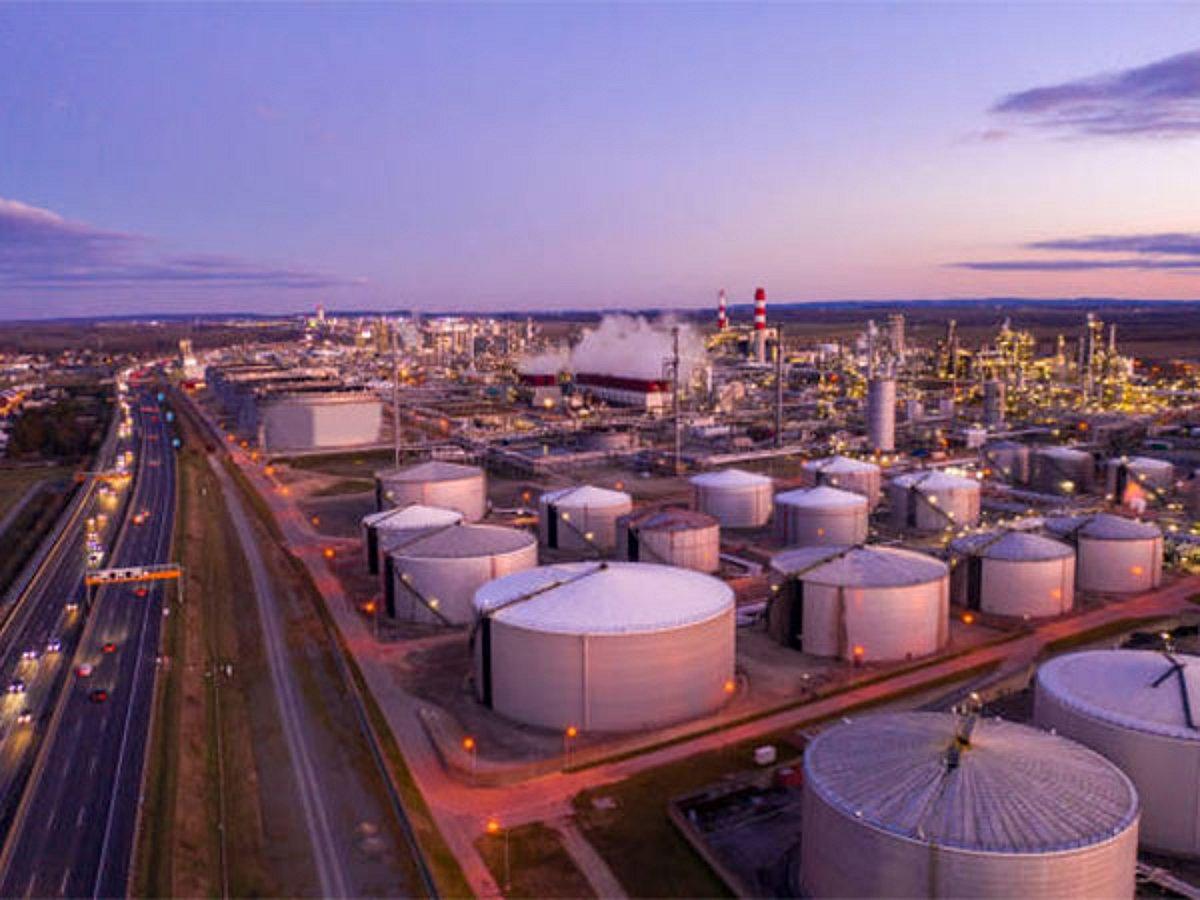
Storage provides an important view of the physical diesel market.
When inventories are high, buyers and traders generally have more supply available to absorb temporary disruptions.
When inventories are low, the same disruption can have a much larger effect on regional availability and pricing.
The latest EIA data shows how closely current U.S. distillate inventories are being watched. Weekly U.S. stocks stood at 107.859 million barrels on September 11, according to the agency’s petroleum data.
The EIA also expects inventories to remain below their recent five-year range for much of 2027.
This does not mean that every country will experience a physical diesel shortage throughout 2027. Diesel markets are regional, and supply conditions can improve when refinery output increases, imports rise or additional exports become available.
However, low inventories leave less room for unexpected disruptions.
Diesel Supply Is a Refining Issue as Much as a Crude Oil Issue
A common assumption is that higher crude production automatically means more diesel availability.
The relationship is more complicated.
Diesel is produced through refining, and the amount available to international buyers depends on refinery capacity, refinery configuration, crude feedstock, operating rates and competing demand for other refined products.
This is why diesel prices can rise sharply even when crude oil prices are not simultaneously reaching the same type of record.
The current market illustrates this distinction. Reuters reports that U.S. diesel prices have risen substantially while refinery capacity constraints have contributed to the pressure on refined products.
For buyers, this means that monitoring crude prices alone is not enough.
What the Current Market Means for EN590 Buyers
For buyers seeking EN590 10 PPM diesel, current market conditions make physical supply availability increasingly important.
A procurement requirement can depend on:
- Product specification
- Available refinery production
- Loading location
- Available export volume
- Storage position
- Required quantity
- FOB or CIF delivery basis
- Freight and logistics
- Destination requirements
- Documentation
- Supplier and cargo verification
A public diesel benchmark therefore should not automatically be interpreted as a firm commercial quotation for EN590.
The actual commercial indication can depend on the product specification, origin, loading point, quantity and delivery terms.
Regional Supply Conditions Matter
The global diesel market is not a single pool of interchangeable supply.
North America, Europe, Asia, the Middle East and Africa can experience very different inventory and refinery conditions at the same time.
For example, the EIA’s current U.S. outlook shows persistent pressure on distillate inventories, while international markets are also responding to changes in refinery output, trade flows and geopolitical disruptions.
For international buyers, the relevant question is therefore not simply:
“What is the global diesel price?”
It is:
“Where is the required specification available, in what quantity, at which loading point, and under what delivery terms?”
That distinction becomes increasingly important when physical inventories are low.
Could More Supply Relieve the Market?
There are several potential sources of relief.
Higher refinery utilization could increase refined-product output where spare capacity is available. Additional exports from countries with surplus production could also help replenish inventories.
The EIA expects global oil production to increase as disrupted production gradually returns, with global inventories eventually rebuilding and crude prices declining in its 2027 outlook.
However, the timing of that recovery remains important for diesel buyers.
If inventories remain low while demand stays firm, unexpected refinery outages, shipping disruptions or changes in export policy could continue producing periods of regional tightness.
What Buyers Should Watch
Companies planning diesel procurement should monitor more than headline prices.
Refinery operating rates
Unexpected refinery maintenance or outages can quickly reduce available diesel volumes.
Inventory levels
Low inventories leave less buffer against supply disruptions.
Export flows
Changes in export volumes from major supplying countries can alter regional balances.
Storage availability
Storage levels and available tank capacity can provide additional information about the physical market.
Freight and logistics
For CIF transactions, freight, insurance, terminal handling and destination logistics can materially affect the delivered cost.
Regional differentials
Price differences between trading hubs can provide signals about where supply is tighter or more readily available.
What Happens Next in the Diesel Market?
The current evidence points to continued market tightness rather than an immediate return to abundant inventories.
The EIA’s September outlook expects U.S. distillate inventories to remain below the five-year low through much of 2027, although its broader forecast also anticipates improving global production and rebuilding inventories as disrupted oil production returns.
That means the market could move through several phases rather than following a single direction.
Additional refinery production and exports could gradually improve availability. Conversely, another major refinery outage or disruption to international supply routes could quickly tighten the market again.
For physical buyers, the practical response is to monitor supply conditions early and evaluate availability based on the actual specification, volume, loading point and delivery basis required.
EN590 Diesel Supply and Procurement
Global Petroleum Advisors provides a supply coordination and procurement pathway for buyers seeking petroleum products including EN590 Diesel 10 PPM.
Buyers can submit their requirements, including product specification, quantity, destination and preferred delivery basis, for review.
Request EN590 Supply
Market conditions can change quickly. Public market references and news reports should not be interpreted as firm commercial quotations. Actual supply availability depends on product specification, origin, loading location, quantity, delivery terms, logistics and prevailing market conditions.
Sources and Market References
Reuters — Global diesel shortage likely to last into 2027 as storage tanks drain
Read the Reuters report
U.S. Energy Information Administration — Short-Term Energy Outlook
View the EIA Short-Term Energy Outlook
U.S. Energy Information Administration — Weekly Distillate Fuel Oil Stocks
View EIA distillate inventory data
U.S. Energy Information Administration — September 2026 STEO archive
View the September 2026 EIA outlook


No Comments